Healthcare is the tape, but it is not one trade
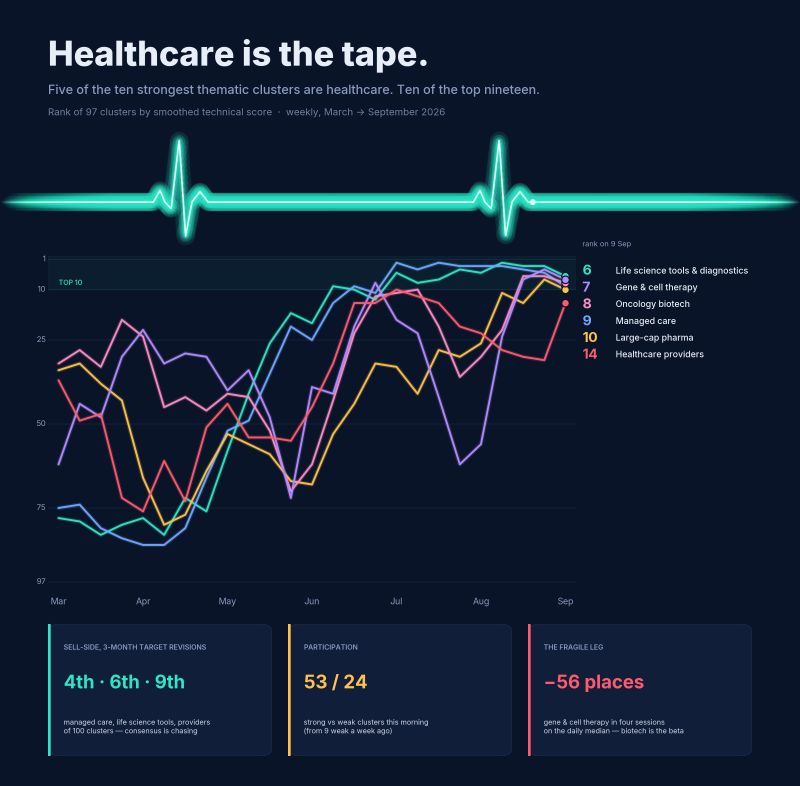
Five of the ten strongest clusters in our thematic map are healthcare: life science tools & diagnostics 6th of 97, gene & cell therapy 7th, oncology biotech 8th, managed care 9th, large-cap pharma 10th. Ten of the top nineteen. No other sector comes close.
Two weeks ago I wrote that the tape and the sell-side disagreed: tools were 2nd on price and 96th on analyst upside. That gap is closing — from the analyst side. On three-month target revisions, managed care now ranks 4th of 100 clusters, tools 6th, healthcare providers 9th, healthcare IT 10th. The consensus is chasing.
We tested whether that matters. It does not. Across four years of our own data, target revisions carry no stable information about the next move, alone or aggregated by cluster. So we read them as context — what the brokers are doing — not as a signal. What the brokers are doing is raising healthcare.
Inside the sector, the paths could not be more different
Tools and managed care have sat in the top ten since July: short-duration cash flows, limited capex, the kind of leadership a repricing of the discount rate produces. Providers just made one of the biggest five-session moves in the universe — up 53 places on the daily median — as the whole complex broadens.
Biotech is the beta. Gene & cell therapy went from 62nd to 7th in six weeks, then lost 56 places in four sessions on the daily median. Rare disease followed it down. Same sector, opposite temperament.
And the map as a whole is thinning: strong clusters 53, weak 24 — a week ago the weak list held nine. Leadership intact, participation lower, with the Fed deciding this week.
What we watch
Whether the defensive healthcare leg — tools, managed care, pharma — holds while the biotech leg swings. If it does, this is a regime. If not, it was a rotation.
Which half of healthcare are you underwriting?
This note started as a post on LinkedIn. Join the conversation there.